U.S. Homebuilder Sentiment Falls to Lowest Level in More Than 14 Years
Rent Magazine Contributor —October 19, 2026
5 Mins Read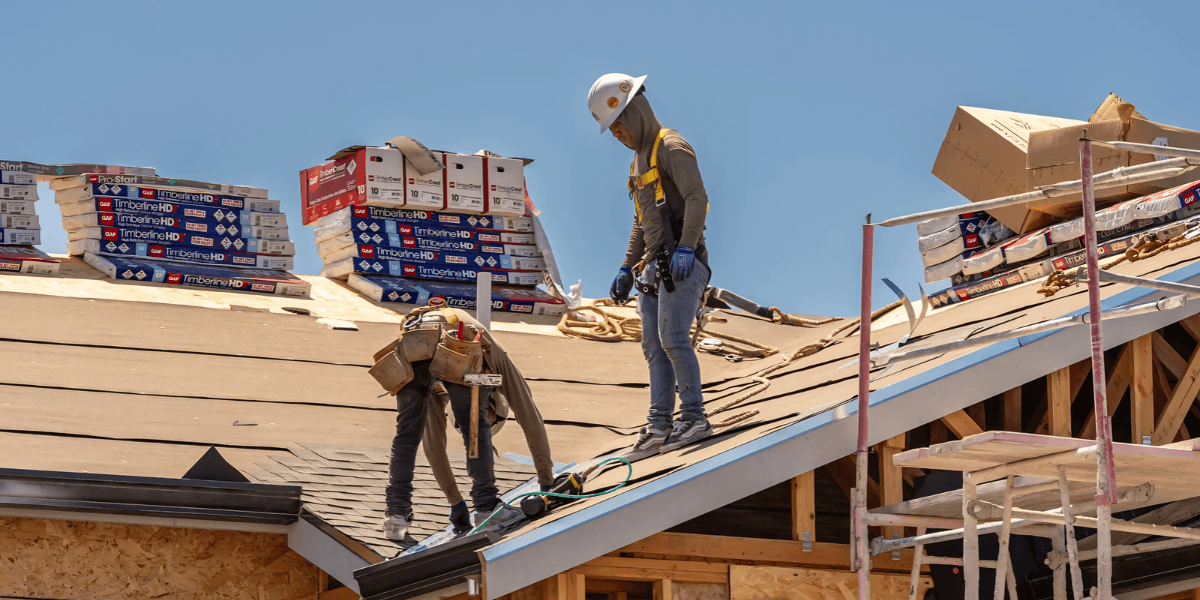
Rising mortgage rates, high home prices and construction expenses are weighing on builders and adding pressure to the housing market.
Confidence among U.S. homebuilders fell sharply in October, reaching its lowest level in more than 14 years as higher mortgage rates and persistent construction costs continued to challenge the housing market. The National Association of Home Builders and Wells Fargo Housing Market Index dropped three points to 29, below economists’ expectations and marking its weakest reading since June 2012.
The index measures homebuilder perceptions of current single-family home sales, expected sales over the coming six months and prospective buyer traffic. Readings below 50 indicate that more builders view conditions as poor than good. The October result therefore reflects widespread concern about the ability to attract buyers and sustain new construction.
The decline points to pressure on both sides of the housing market. Buyers face expensive mortgages and elevated home prices, while builders must manage labor, materials, financing and inventory costs.
Mortgage Rates Reduce Purchasing Power
The average rate on a 30-year fixed mortgage reached 7.40%, its highest level in nearly three years, according to the report. Higher mortgage rates increase the monthly cost of financing a home and can reduce the amount a household qualifies to borrow.
That effect is especially significant when home prices remain elevated. Buyers who could afford a property under lower borrowing costs may find that the same home now requires a substantially larger monthly payment. Some households respond by seeking less expensive properties, delaying a purchase or remaining in rental housing.
For homebuilders, weaker affordability can translate into fewer sales and greater uncertainty about how quickly new homes will be absorbed by the market. Builders may respond by adjusting prices, offering incentives or changing the timing of projects.
The October index showed weakness across several components. Current sales conditions fell to 33, expectations for sales over the next six months dropped to 32, and prospective buyer traffic declined to 18. The buyer-traffic measure was particularly low, indicating that builders were seeing limited interest from potential purchasers visiting developments and model homes.
Builders Turn to Discounts and Incentives
With buyers under pressure, many builders have been using financial incentives to support sales. The report found that 43% of builders had reduced home prices, the highest share since 2020. The average reduction remained at approximately 6%, while 65% offered sales incentives.
Such incentives can take several forms, including assistance with closing costs, upgrades, or financing arrangements offered through a builder’s mortgage partner. These measures may help some buyers complete a purchase, but they also affect the economics of each sale.
Price reductions can narrow profit margins, particularly when construction costs remain high. Incentives may preserve the headline price of a home while reducing the effective amount a buyer pays, but they still represent a cost to the builder.
For prospective purchasers, advertised incentives can make a new home more attainable. However, buyers still need to evaluate the full cost of ownership, including loan terms, property taxes, insurance, maintenance and any conditions attached to an offer.
Construction Costs and Supply Pressures
Mortgage rates are not the only concern for homebuilders. The industry continues to contend with higher costs for some building materials, labor shortages, construction-loan expenses and delays.
Tariffs can add uncertainty to the price of materials and products used in construction. Labor availability can also affect schedules and project budgets, particularly when builders depend on specialized trades. Delays can increase carrying costs and complicate the coordination of subcontractors, deliveries and inspections.
The report also noted that unsold inventory is discouraging additional single-family construction. When completed homes remain on the market longer than expected, builders may hesitate to start new projects until existing inventory is reduced.
This creates a difficult balancing act. Building fewer homes may help prevent an oversupply of new properties in a particular market, but it can also limit future additions to the housing stock. The effect depends on local demand, the number of existing homes for sale and the pace at which new households form.
Housing Affordability Remains a Wider Challenge
The weakness in builder sentiment reflects broader affordability concerns that affect both prospective buyers and the rental market. Households unable to purchase a home may remain renters for longer, increasing demand for rental accommodation in some areas. Yet rental affordability can also be strained by housing shortages, local income levels and the cost of developing new properties.
The relationship between homeownership and renting is not uniform across the country. Local employment conditions, population growth, available housing and construction activity can create very different outcomes from one region to another.
Lower builder confidence also matters for employment and related industries. Residential construction supports jobs in building trades, materials manufacturing, transportation, real estate services and home furnishings. If projects are postponed or reduced, the effects can spread beyond builders themselves.
However, a national sentiment index does not predict the same outcome for every market. Builders in locations with strong employment and sustained household growth may experience different conditions from those in areas where demand is weaker or inventory is elevated.
What the October Reading Signals
The index provides a measure of industry sentiment rather than a direct count of homes being built or sold. Its decline suggests that builders see mounting obstacles, but actual construction and sales data are needed to determine how activity changes over time.
Future conditions will depend partly on mortgage rates, wage and employment trends, construction costs and the ability of households to afford monthly payments. If financing becomes less expensive, some buyers who postponed purchases may return. If rates and costs remain high, builders may continue relying on incentives and limiting new starts.
The October reading underscores the pressure created when housing prices and financing costs remain high at the same time. Builders are attempting to sell homes in an environment where many households have limited room in their budgets, while development costs continue to constrain pricing decisions.
For renters, the broader implications are also important. Slower home construction can affect the future housing supply, while affordability challenges may keep some households in rental accommodation longer than they planned. The scale of those effects will vary by market, but the national decline in builder confidence highlights how financing conditions can shape the availability and cost of housing across the country.

Rent Magazine Contributor
This article features partner, contributor, or branded content from a third party. Members of the Rent Magazine editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
Related Posts
 U.S. Housing Market Faces an Affordability Challenge as Home Sales Remain Sluggish
Rent Magazine Contributor —October 17, 2026
 U.S. Multifamily Rents Edge Higher in Third Quarter as Rental Supply Pressures Begin to Ease
Rent Magazine Contributor —October 11, 2026